2025 Credit Reporting Complaints: Issues and Investigation Problems
By CreditHound. Published September 18, 2026. Data retrieved September 18, 2026, 16:46 UTC.
Scope: published complaint records in the CFPB Consumer Complaint Database with a date received in 2025, product "Credit reporting or other personal consumer reports", sub-product "Credit reporting". This is a dated snapshot of a public database, not a live counter, and it is not endorsed by the CFPB.
Key findings
501,566 published 2025 credit-reporting complaint records said an investigation did not fix a report error. That is the sub-issue those consumers selected on the complaint form. It is a description of what people said happened to them, not a finding that a company broke the law, not a count of unique people, and not a dispute failure rate.
4,800,102
Selected published complaint records
Credit reporting sub-product, received in 2025. Denominator for shares labeled all selected records. Investigation shares use 856,417 records.
856,417 (17.8%)
Investigation-related records
Share of all 4,800,102 selected records.
501,566 (58.6%)
"Investigation did not fix an error"
Share of the 856,417 investigation records; 10.4% of all selected records.
These numbers describe a public complaint database. They are not evidence about CreditHound's own results, and they say nothing about whether any individual complaint was justified.
2024 to 2025 comparison
Published complaint records selecting "Their investigation did not fix an error on your report" rose +96.04%, from 255,848 in 2024 to 501,566 in 2025. That growth needs context: all selected records roughly doubled. The not-fixed share of investigation-related records rose +2.52 percentage points, while its share of all selected records fell 0.40 percentage points.
Both years use the exact same product, sub-product, issue and sub-issue labels, counted by date received (January 1 inclusive to January 1 of the next year, exclusive). 2024 to 2025 is the earliest adjacent full-year pair available under this exact current taxonomy; older categories are not mapped or mixed, and two years are not a longer trend. Counts were retrieved September 28, 2026 (UTC) and may change, because the CFPB generally updates the database daily. The CFPB says the database is not representative of all consumers' experiences.
| Measure | 2024 | 2025 | Change |
|---|---|---|---|
| All selected credit-reporting complaint records | 2,359,274 | 4,800,102 | +2,440,828 (+103.46%) |
| Problem with a company's investigation into an existing problem | 456,517 | 856,417 | +399,900 (+87.60%) |
| Their investigation did not fix an error on your report | 255,848 | 501,566 | +245,718 (+96.04%) |
| Investigation-related records as a share of all selected records | 19.35% | 17.84% | -1.51 percentage points |
| Not-fixed sub-issue as a share of investigation-related records | 56.04% | 58.57% | +2.52 percentage points |
| Not-fixed sub-issue as a share of all selected records | 10.84% | 10.45% | -0.40 percentage points |
Units are published complaint records, which are consumer allegations - not unique consumers, verified errors, violations, failure rates, a population sample, CreditHound leads or qualified cases. Exact six-decimal values are in the comparison downloads below.
Issues consumers selected
Every label below is preserved exactly as it appears in the public database. Shares use the 4,800,102 selected records as the denominator. Labels with a positive but very small share are shown as "<0.1%" rather than rounded down to zero.
| Issue label | Records | Share of all selected |
|---|---|---|
| Incorrect information on your report | 2,809,657 | 58.5% |
| Improper use of your report | 1,096,097 | 22.8% |
| Problem with a company's investigation into an existing problem | 856,417 | 17.8% |
| Problem with fraud alerts or security freezes | 15,075 | 0.3% |
| Unable to get your credit report or credit score | 14,870 | 0.3% |
| Credit monitoring or identity theft protection services | 7,977 | 0.2% |
| Other supplied issue labels (5 labels) | 9 | <0.1% |
Show the 5 remaining issue labels (9 records in total)
- Dealing with your lender or servicer: 4 records (<0.1%)
- Problems at the end of the loan or lease: 2 records (<0.1%)
- Managing an account: 1 record (<0.1%)
- Problem with a purchase shown on your statement: 1 record (<0.1%)
- Struggling to repay your loan: 1 record (<0.1%)
These labels are unusual inside this sub-product and are kept exactly as supplied. They are not dropped, merged or corrected here, and all of them appear in the downloads.
Inside the investigation complaints
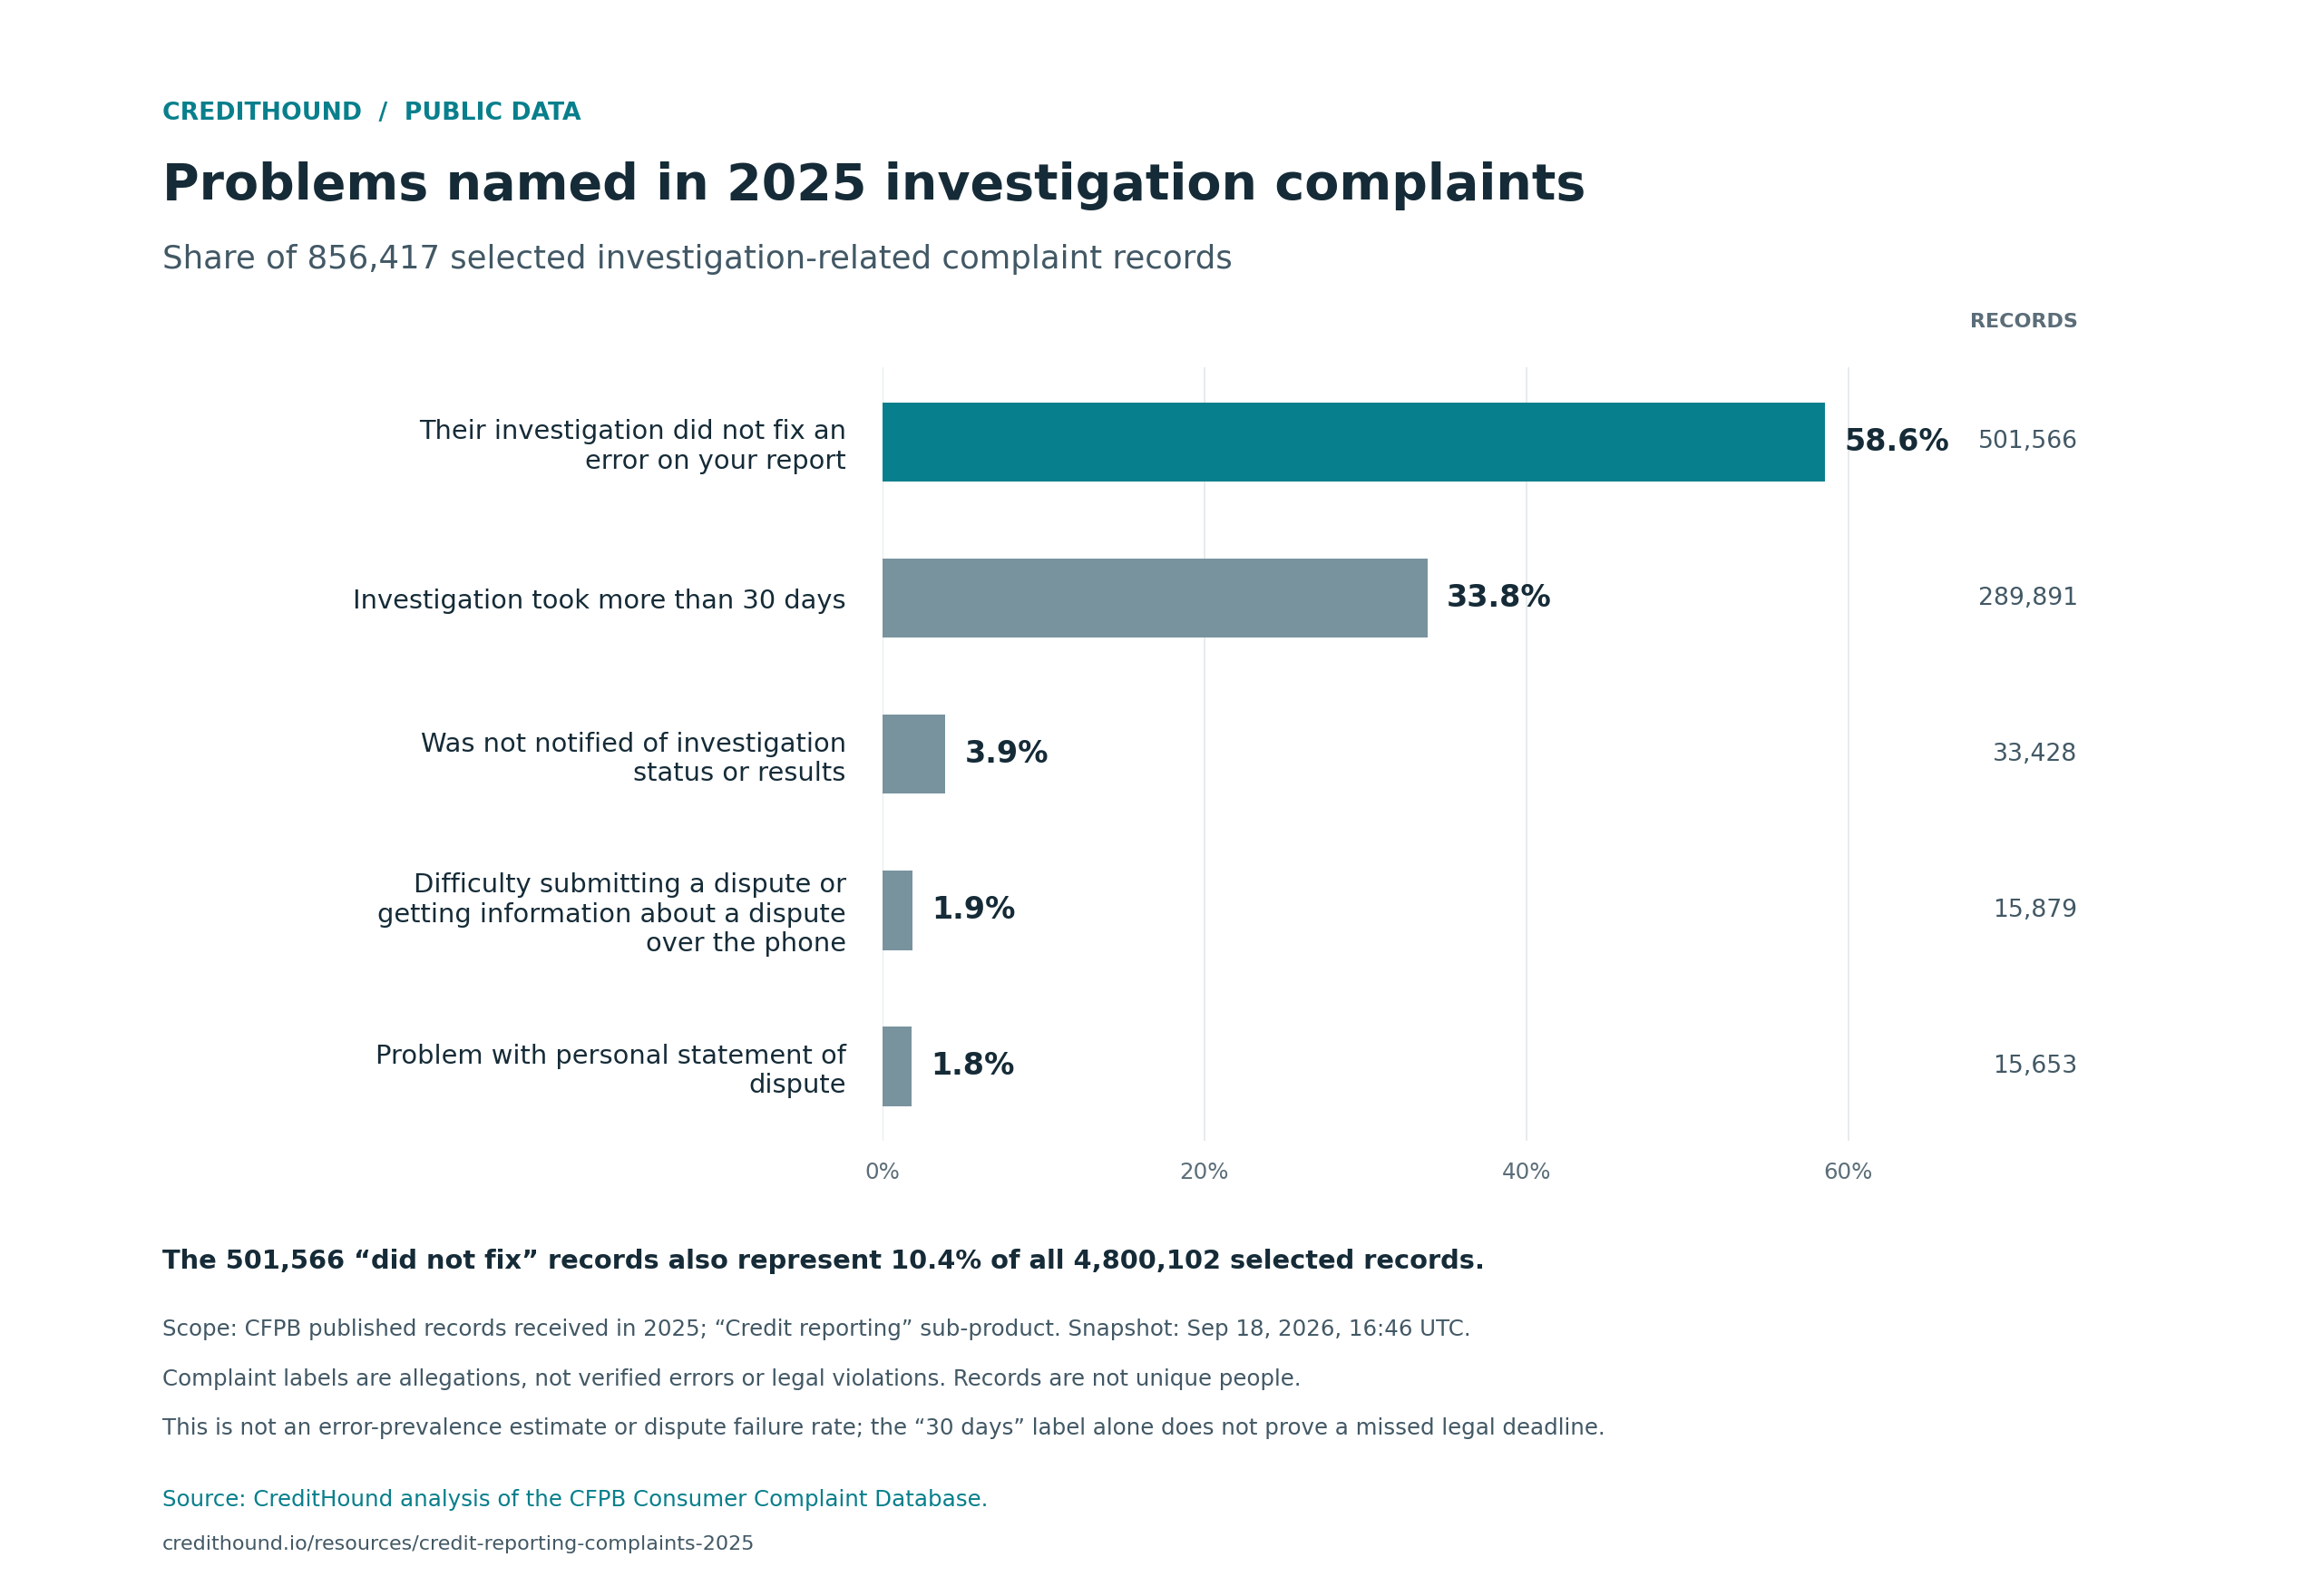
The parent denominator for this table is the 856,417 records filed under "Problem with a company's investigation into an existing problem".
| Sub-issue label | Records | Share of investigation records | Share of all selected |
|---|---|---|---|
| Their investigation did not fix an error on your report | 501,566 | 58.6% | 10.4% |
| Investigation took more than 30 days | 289,891 | 33.8% | 6.0% |
| Was not notified of investigation status or results | 33,428 | 3.9% | 0.7% |
| Difficulty submitting a dispute or getting information about a dispute over the phone | 15,879 | 1.9% | 0.3% |
| Problem with personal statement of dispute | 15,653 | 1.8% | 0.3% |
The "Investigation took more than 30 days" label records what the complainant selected. It does not establish that any investigation was legally overdue: the timing rules have exceptions, and the database does not report how a given investigation was handled.
Chart
How to read these numbers
Issue and sub-issue labels describe what the person filing chose from a fixed list on the CFPB complaint form. They are the consumer's description of the problem. Publication of a complaint, or a company's response to it, is not proof that anything was resolved or that anything was wrong.
Aggregates like these cannot tell you how common credit-report errors are across the population, whether any particular claim would succeed in court, or whether a given situation would qualify for attorney review. The database is not a representative sample, records are not deduplicated to unique people, and one person can file more than once. We publish no company rankings, no year-over-year comparison and no causal claim here.
- The CFPB database is not a representative sample of all consumers.
- A complaint is an allegation, not a verified error, legal violation, qualified case or successful claim.
- Complaint records are not deduplicated to unique consumers or underlying disputes.
- Issue and sub-issue labels are preserved from the public database; this analysis does not recode them.
- The denominator is the selected published credit-reporting complaint records; it excludes the other-personal-consumer-report sub-product.
- The database can change after retrieval, so this is a dated snapshot rather than a live total.
- No narratives, names, contact details, complaint IDs, states, ZIP codes or company-level rankings are included.
- A company response or timely response is not proof that the underlying report was corrected.
Methodology
The figures come from a single query against the public CFPB complaint search API, plus two independent verification queries. Only aggregate counts were used in this analysis; no narratives or consumer-level records are included in the downloads.
- Source query: https://www.consumerfinance.gov/data-research/consumer-complaints/search/api/v1/?date_received_min=2025-01-01&date_received_max=2026-01-01&product=Credit+reporting+or+other+personal+consumer+reports%E2%80%A2Credit+reporting&size=1&no_aggs=false
- Date received from 2025-01-01 (inclusive) to 2026-01-01 (exclusive).
- Filter: product and sub-product supplied together as the bullet-separated value "Credit reporting or other personal consumer reports•Credit reporting". The other-personal-consumer-report sub-product is excluded.
- Unit of analysis: published complaint records. No deduplication to people or to underlying disputes.
- Tables use the facet counts for issue and sub-issue. The query's product facet can ignore the product filter (it reports 5,452,105), so it is not used as a denominator anywhere. The denominator is the query's hits total, 4,800,102.
- Verification: total relation "eq", timed_out false, failed shards 0, issue counts sum to the total, the five investigation sub-issue counts sum to 856,417, and two independently filtered queries returned 856,417 and 501,566.
- Counts are exact. Shares are rounded to one decimal for display, and percentages in the downloads are rounded to six decimal places; the downloads also carry the record unit. Positive shares under 0.1% are displayed as "<0.1%".
- Retrieval timestamp: 2026-09-18T16:46:35.133540+00:00.
- The public database changes as complaints are published, so these totals are a snapshot.
Reference material: CFPB Consumer Complaint Database, API documentation, field reference, CFPB notes on using complaint data, and the complaint form product and issue options.
Cite and download
You are welcome to quote or reuse these aggregates with attribution. The citation text below is always visible, so it works without JavaScript.
CreditHound, "2025 Credit Reporting Complaints: Issues and Investigation Problems" (https://credithound.io/resources/credit-reporting-complaints-2025). CreditHound analysis of the CFPB Consumer Complaint Database, complaints received 2025-01-01 through 2026-01-01 (exclusive); snapshot retrieved September 18, 2026, 16:46 UTC. Counts are published complaint records, which are consumer allegations, not verified errors or proven violations.
Both files are free, need no sign-in, and contain the same aggregate counts shown above: totals, every issue label, and every investigation sub-issue label. They contain no complaint narratives, no complaint IDs and no consumer records.
The comparison files hold only the three 2024 and 2025 aggregate counts, their changes, the three shares with percentage-point changes, the exact filter labels and date boundaries, the retrieval date, documentation links, formulas and caveats.
Embed the chart
Plain HTML, no script and no tracking. A link back is welcome but is not required, and using this chart does not imply that CreditHound endorses your page.
Data dictionary
Column names below are exactly the headers in the CSV download.
| Column | Definition |
|---|---|
| section | Row level: "total" for the overall count, "issue" for a parent issue label, "investigation_sub_issue" for a child label inside the investigation issue. |
| label | The issue or sub-issue label exactly as published in the CFPB database. Labels are not recoded here. |
| parent | The label this row sits under. Issue rows sit under the overall total; sub-issue rows sit under the investigation issue. Because children are already counted inside their parent, parent and child counts must never be added together. |
| complaint_records | Count of published complaint records carrying that label. Records, not unique people: one person can file more than once. |
| share_of_parent_percent | Percentage of the parent row's records. Issue rows use the 4,800,102 all-selected-records denominator; investigation sub-issue rows use the 856,417 investigation-records denominator. Rounded to six decimals in the downloads. |
| unit | Fixed text repeating the counting unit: published complaint records, not unique people, credit-report errors or proven violations. |
All rows are as of the September 18, 2026, 16:46 UTC snapshot of complaints received in 2025. The JSON download carries the same values with the same two denominators.
Your next step
Does this sound like your situation? Your own records matter more than the totals.
- Printable dispute evidence checklist lists what to keep and gives you a worksheet.
- Dispute came back verified but is still wrong covers an unchanged result.
- The CFPB explains options when you disagree with dispute results.
Want help checking what looks wrong?
Start with a free check. You can begin even if you are still gathering documents. Nothing on this page decides whether your situation qualifies for anything.
Start my free error checkNo credit card. No obligation to hire a law firm.
CreditHound is not a law firm and does not write, send, or file disputes for you. We help you gather the details about what looks wrong, and with your consent your situation can go to an independent partner law firm for review. This page is general consumer information, not legal advice.